Whether an Insurer Rates a Pomsky as a Husky
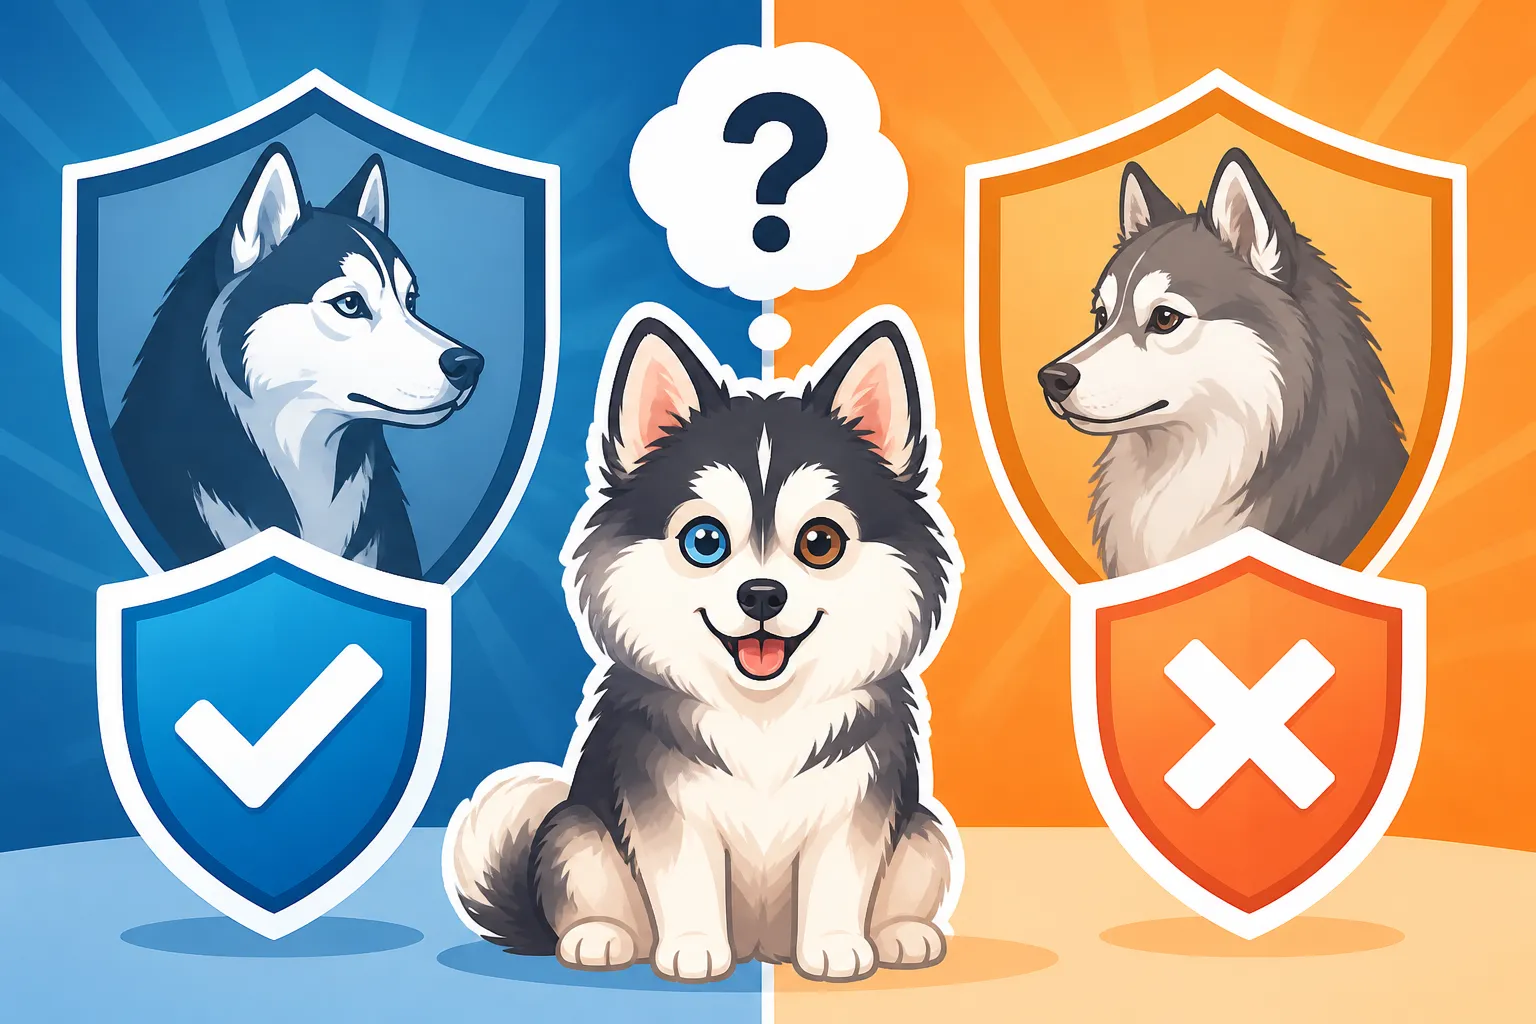
One of the most common head-scratchers for new Pomsky parents, or even those just dreaming of bringing one home, is navigating the confusing world of pet insurance. You’ve got this delightful, often miniature version of a Husky, but when you go to get them covered, you're left wondering if the insurance company will see your beloved Pomsky as a "Siberian Husky," a "Pomeranian mix," or simply a generic "mixed breed." This guide is here to unravel that mystery, helping you understand how insurance companies typically classify these wonderful hybrids and what that means for your coverage and premiums.
The Mixed Breed Dilemma: Why Classification Matters for Your Pomsky
It can be incredibly frustrating trying to figure out how a unique hybrid like a Pomsky fits into the neatly organized boxes of pet insurance companies. You've got this adorable, spirited pup, and suddenly you're wading through jargon about purebred risks and breed-specific exclusions, wondering if your Pomsky is going to be seen as a mini Husky or something else entirely. The truth is, how your insurance provider classifies your Pomsky can significantly impact everything from your monthly premiums to what conditions are covered, and even the waiting periods for certain genetic predispositions. This isn't just semantics; it's about making sure your furry family member is protected when they need it most.
The Purebred vs. Mixed Breed Divide in Insurance
Historically, pet insurance was structured heavily around purebred dogs. Each recognized breed comes with a well-documented list of potential genetic health issues, common temperaments, and expected lifespans. This data allows insurers to accurately assess risk and price policies accordingly. For example, a purebred Labrador Retriever might have known predispositions to hip and elbow dysplasia, while a purebred Yorkshire Terrier might be more prone to patellar luxation or tracheal collapse. These breed-specific health concerns are often factored into the risk assessment for purebred policies.
However, mixed breeds present a different challenge. A traditional "mutt" often benefits from what's sometimes called "hybrid vigor," a theory suggesting that a wider gene pool can lead to fewer inherited conditions compared to a more inbred purebred line. For some mixed breeds, this can translate to lower insurance premiums because their overall risk profile might appear less concentrated. But the Pomsky isn't just any mixed breed; it's a specific cross of two distinct purebreds, which means insurers have to consider the genetic legacy from both sides, often without the benefit of decades of established data for the cross itself.
Understanding Breed-Specific Risks from Both Sides
When an insurer looks at your Pomsky, they're essentially looking at a genetic lottery ticket drawn from both the Siberian Husky and the Pomeranian. Each parent breed brings its own set of potential health challenges to the table. Huskies, for example, are known for certain eye conditions like juvenile cataracts and progressive retinal atrophy, as well as hip dysplasia. Pomeranians, on the other hand, might be predisposed to patellar luxation, collapsing trachea, and dental crowding. You might be concerned about The Collapsing Trachea a Pomsky Gets From the Pomeranian or The Eyes a Pomsky Gets From the Husky, both very real possibilities for your Pomsky.
The insurer's job is to figure out which of these inherited traits your Pomsky might be more susceptible to, even if they aren't fully expressed. This risk assessment isn't about predicting your dog's individual health, but rather about statistical probability based on their lineage. Since the Pomsky is a relatively new and unregulated crossbreed, comprehensive, long-term health data specifically for Pomskies is still accumulating. This lack of extensive historical data makes it a bit trickier for insurers to slot them into a neat category, often leading to varied approaches across different providers.
How Insurers Approach Pomskies: More Than Just Appearance
The biggest misconception is often that insurers just look at a Pomsky and label them based on their appearance. While their striking Husky-like features or fluffy Pomeranian coats are certainly eye-catching, insurance companies delve much deeper than surface aesthetics. They consider a complex interplay of genetic predispositions, average size, known behaviors, and the overall statistical risk associated with the parent breeds. It's not about whether your Pomsky looks like a miniature Husky, but about what genetic baggage they might carry.
The Husky Influence: Traits and Health Concerns
Many Pomsky owners are drawn to the breed because of their resemblance to a miniature Siberian Husky. And indeed, the Husky parentage brings with it several defining characteristics. Huskies are known for their high energy levels, strong prey drive, and propensity for escape artistry. From an insurance perspective, this can sometimes translate to a higher risk of accidents, such as injuries from running away, or incidents involving other animals. If you have a Pomsky who's a true escape artist, you already know the worry that comes with that. This is especially true given the breed's intelligence and ability to open gates or even scale fences – a topic we explore in The Pomsky Escape Artist in a Twenty Pound Body.
Beyond behavior, Huskies also contribute a specific list of health concerns. As mentioned, certain eye conditions are common, and Hip Dysplasia in a Twenty Pound Pomsky is a genuine concern, even in smaller dogs. Insurers will certainly be aware of these potential issues, and some might consider these Husky-related risks when pricing a policy for a Pomsky. They're looking at the potential cost of treating these conditions over The Twelve to Fifteen Years a Pomsky Lives.
The Pomeranian Contribution: Size and Other Factors
On the other side of the genetic coin, the Pomeranian parentage brings its own set of influences. Pomeranians are a small toy breed, and while Pomskies vary in size (with many falling into the 15-30 pound range, but some reaching larger weights as detailed in What a Pomsky Actually Weighs), the influence of a small breed ancestor is significant. Smaller dogs often have different types of health issues compared to larger breeds. For instance, Slipping Kneecaps in a Pomsky, known as patellar luxation, is much more prevalent in Pomeranians and other small breeds. Dental problems, specifically dental crowding due to their small mouths, are also a common concern that can lead to costly veterinary dental procedures down the line.
The Pomeranian side can also influence temperament, often contributing to a more alert and sometimes more vocal nature. While generally affectionate, some Pomeranians can be more prone to suspicion towards strangers. From an insurance standpoint, the smaller size could be seen as a lower risk for certain types of injuries (like being hit by a car, though still a major risk), but it introduces higher risks for other conditions. Insurers try to balance these opposing forces when determining how to classify your unique companion.
What Data Insurers Actually Use
Given that Pomskies aren't officially recognized by major kennel clubs, there isn't a standardized "Pomsky" breed profile for insurers to refer to. This lack of formal recognition means insurance companies have to get creative with their classification. They often rely on a combination of factors:
- Parent Breed Information: This is usually the primary data point. They'll look at the known health and behavioral risks of both the Siberian Husky and the Pomeranian.
- Actual Size and Weight: Your Pomsky's adult size and weight play a role. A larger Pomsky might lean more towards Husky-related risks, while a smaller one might resemble a Pomeranian mix.
- Individual Health History: If your Pomsky has any pre-existing conditions, these will almost certainly be excluded from coverage, regardless of breed classification.
- Age: Younger puppies are generally cheaper to insure, but as they age, the risk of developing conditions increases.
- "Mixed Breed" Designation: Many insurers will simply classify a Pomsky as a "mixed breed." This can sometimes be advantageous, as mixed breeds occasionally have lower premiums due to the perceived "hybrid vigor" and a generalized risk profile rather than specific high-risk breed issues. However, it also means they might not have specific coverage considerations that a purebred policy might offer.
Essentially, an insurer might use a sliding scale or a blended approach. They are less likely to strictly rate a Pomsky as a purebred Husky because the Pomeranian influence is undeniable, both in size and potential health predispositions. It's more common to see them classified as a mixed breed with consideration given to the genetic backgrounds.
| Classification Type | Characteristics | Potential Impact on Premiums/Coverage |
|---|---|---|
| Purebred Husky | Based solely on Husky appearance/traits. | Higher premiums due to Husky-specific risks (e.g., hip, eye issues). |
| Purebred Pomeranian | Based solely on Pomeranian appearance/traits (rare for Pomsky). | Higher premiums due to Pomeranian-specific risks (e.g., patella, trachea). |
| Mixed Breed (General) | No specific breed focus, generic mixed breed risk assessment. | Often more moderate premiums; may not factor in specific parent breed risks as strongly. |
| Mixed Breed (Named Parents) | Recognizes both Husky & Pomeranian parentage. | Blended risk assessment, considers predispositions from both parents. |
| "Designer Breed" | Some specialized insurers might use this, rare for general. | Varies widely; might include specific exclusions or requirements. |
Navigating the Insurance Landscape for Your Pomsky
Finding the right pet insurance for your Pomsky can feel like a labyrinth, especially with the ambiguity around their breed classification. You want the best for your furry friend, and that means a policy that truly protects them without breaking the bank. Understanding how to compare policies and what questions to ask is crucial to making an informed decision. Remember, the goal is peace of mind, knowing that if something unexpected happens, you're not facing massive veterinary bills alone. What a Pomsky's Vet Bills Look Like can be quite substantial when serious issues arise.
Comparing Policies: What to Look For
When you're sifting through pet insurance options, don't just jump at the lowest premium. Instead, delve into the details of what each policy actually covers. Look closely at:
- Deductibles: This is the amount you pay out of pocket before your insurance kicks in. Lower deductibles mean higher premiums, and vice-versa.
- Reimbursement Levels: Most policies offer 70%, 80%, or 90% reimbursement after your deductible.
- Annual Limits: This is the maximum amount the insurance company will pay out in a policy year. Some offer unlimited plans, which can be invaluable for chronic conditions.
- Coverage for Accidents and Illnesses: Ensure it covers common issues like broken bones, infections, and diseases. This is the bread and butter of pet insurance.
- Wellness Options: Some policies offer add-ons for routine care like vaccinations, annual exams, and parasite prevention. These are often separate from accident/illness coverage.
- Waiting Periods: Be aware of how long you have to wait after purchasing a policy before certain coverages become active. There are often shorter waiting periods for accidents and longer ones for illnesses or orthopedic issues.
- Exclusions: This is perhaps the most important part. Read the fine print! Are there any breed-specific exclusions? Are pre-existing conditions defined clearly? For instance, some policies might have specific clauses about conditions common to the parent breeds.
Companies like Healthy Paws are well-regarded for their comprehensive accident and illness plans, often focusing on major medical events. Others might have more flexibility in terms of wellness packages.
The Impact on Premiums and Coverage
How an insurer classifies your Pomsky directly impacts your premiums and the scope of your coverage. If they lean towards a "mixed breed" classification, your premiums might be lower than if they consider your Pomsky predominantly a Husky, which can sometimes be viewed as a higher-risk breed due to specific genetic issues. However, if they categorize it broadly as a mixed breed, you might also find that policies are less tailored to the unique predispositions of Siberian Huskies and Pomeranians.
For example, if your Pomsky develops The Collapsing Trachea a Pomsky Gets From the Pomeranian, which is a Pomeranian predisposition, will the mixed-breed policy cover it without question, or will there be scrutiny if the policy isn't specific to small-breed respiratory issues? This is where getting clarity upfront is crucial. Some insurers might even offer different rates for F1 versus F2 Pomskies, reflecting the perceived health predictability discussed in Whether an F1 Pomsky Is Healthier Than An F2. The key is to get quotes from multiple providers and compare their stated classification for your Pomsky.
What to Ask Your Insurance Provider
Don't be shy about asking direct questions when getting a quote. You need clear answers specific to your Pomsky. Here are some essential questions:
- "How do you classify a Pomsky for insurance purposes? Is it a mixed breed, or do you list it under one of its parent breeds?"
- "Are there any breed-specific exclusions or limitations that apply to Pomskies, considering their Husky and Pomeranian heritage?"
- "What are your waiting periods for conditions like hip dysplasia or patellar luxation, which are common in the parent breeds?"
- "If my Pomsky develops a condition common to Huskies (e.g., certain eye issues), how would that be covered?"
- "If my Pomsky develops a condition common to Pomeranians (e.g., collapsing trachea), how would that be covered?"
Having these conversations upfront can save you a lot of heartache and financial strain later. It helps you understand what you're truly signing up for and whether the policy genuinely meets the potential needs of your unique Pomsky.
Practical Strategies for Insuring Your Unique Companion
Insuring a Pomsky isn't just about picking a policy; it's about making smart, proactive choices that set your furry friend up for lifelong health and protection. Because of their unique hybrid status, Pomsky owners have a bit more homework to do than those with purebred dogs, but the effort is absolutely worth it. Thinking ahead and documenting everything can make a huge difference when it comes to claims and understanding your coverage.
Documenting Your Pomsky's Pedigree and Health
Even if your Pomsky doesn't have official "papers" in the traditional sense of a purebred, a responsible breeder should provide you with information about the parent dogs. Keep meticulous records of this, including the parents' breed (Siberian Husky and Pomeranian, of course), their weights, and any health clearances they received. For example, if your breeder shared OFA certifications for the Husky parent's hips or patella evaluations for the Pomeranian parent, keep copies. This documentation can sometimes help an insurer understand the genetic background more clearly and potentially influence how they assess risk, especially if there's a question about specific conditions like hip dysplasia.
Beyond parental history, maintain a comprehensive health record for your Pomsky from day one. This includes vaccination records, annual check-up results, and any minor illnesses or injuries, even if they seem insignificant at the time. A detailed veterinary history can prove invaluable if you ever need to make a claim, especially to establish that a condition wasn't "pre-existing" before your policy's inception. This also includes ensuring your Pomsky receives regular preventative care, such as annual Whether a Pomsky Needs a CAER Exam to monitor their eye health, which can catch issues early.
Exploring Different Insurance Types
Pet insurance isn't a one-size-fits-all solution. There are generally three main types of policies you'll encounter, and understanding their differences will help you choose the best fit for your Pomsky:
- Accident-Only: These policies are usually the most affordable and cover injuries from accidents (e.g., broken bones, poisonings, cuts). They do not cover illnesses. While better than nothing, given the predispositions from both Husky and Pomeranian lines, this might not be sufficient for a Pomsky.
- Accident & Illness: This is the most popular and recommended type of policy. It covers a wide range of unexpected accidents and illnesses, from infections and allergies to cancer and orthopedic conditions. This is where most Pomsky owners find the best value for comprehensive protection. Many reputable providers, including Healthy Paws, focus on this type of robust coverage.
- Wellness/Routine Care Add-ons: These are often supplemental packages that can be added to an Accident & Illness plan. They help cover the costs of routine preventative care like annual exams, vaccinations, heartworm medication, and sometimes even dental cleanings. While not strictly "insurance" for unexpected events, they can help budget for predictable veterinary expenses. Some retailers like Chewy offer auto-ship options for regular medications or food, and might also provide information on wellness plans that complement your insurance.
Deciding between these depends on your budget and your comfort level with potential out-of-pocket costs for illnesses. Considering the initial investment in a Pomsky, often ranging from The Fifteen Hundred to Five Thousand a Pomsky Costs, adding comprehensive insurance is a wise financial decision for the long term.
Leveraging Brand Offerings for Pomsky Parents
While insurance companies are the direct providers of policies, many related brands in the pet industry offer complementary services or resources that can make managing your Pomsky's health and costs easier.
For instance, companies like Chewy are not just for buying food and toys; they often have extensive online pharmacies where you can fill prescriptions for medications (which, if vet-prescribed and covered, you'd then submit to your insurer for reimbursement). They might also offer resources or even partnerships that could lead to discounts on pet services or provide information that helps you understand common pet health issues. Some subscription food services, like Ollie, focus on fresh, healthy diets. While pet food itself isn't covered by traditional insurance, a healthy diet can contribute to overall well-being, potentially reducing the frequency of certain health issues that could lead to claims.
Always check if your chosen pet insurance provider, whether it's Healthy Paws or another reputable company, has any affiliations or preferred vet networks that could streamline the claims process or offer additional benefits. The ultimate goal is to create a holistic plan for your Pomsky's health, combining preventative care, a good diet, and robust insurance to cover the unexpected.
Disclaimer
This article is for general informational purposes only and does not constitute professional advice. Laws, prices and regulations vary by location and change over time. Consult a qualified professional for guidance on your specific situation.